The Freedom Strategy invests your assets long-term in selected stocks, precious metals, and Bitcoin, within a tax-advantaged framework. Returns remain invested during the term and are only taxed upon payout. At the same time, assets can be transferred to the next generation early.
100.000
Minimum investment in Euros
250.000
From this amount also for succession planning
Switzerland
Held at St. Galler Kantonalbank in Switzerland
62/12
The rule to which the half-taxation is linked
Investments are made as in the Shielding Strategy, which we developed together with Marc Friedrich: in selected individual stocks, physically backed gold and silver, a Bitcoin ETP, and a position in Swiss francs. The portfolio remains the same; only the legal framework differs.
The framework is formed by a so-called insurance wrapper, and the assets are held at St. Galler Kantonalbank. This results in significant tax differences: returns within the policy are not taxed on an ongoing basis, but only upon payout. If certain conditions are met, only half of the return is taxed.
The second difference concerns asset succession. A policy can be transferred during one's lifetime, at its current value and utilizing current tax-free allowances. Future returns then already accrue to the recipient. Therefore, we recommend the strategy for succession planning for amounts of 250,000 EUR or more.
Both advantages are subject to conditions. These are listed in full below.
A regular brokerage account and an insurance wrapper are treated differently for tax purposes: when rebalancing, at the end of the term, and in the event of death. This description applies to private investors who are subject to unlimited tax liability in Germany.
Occasion
In a standard securities account
In an insurance wrapper
When we rebalance
In a standard securities account
A flat-rate withholding tax is incurred on every realized gain, including a solidarity surcharge, totaling approximately 26.4%. This amount flows out of the securities account and is no longer available for investment.
In an insurance wrapper
No ongoing tax is incurred within the policy. The full amount remains invested. A tax is only incurred upon payout. Over long periods, this is usually the largest of the three effects.
At the end of the term
In a standard securities account
Capital gains tax on the entire profit, regardless of how long you have held the investment.
In an insurance wrapper
Only half of the gain is taxed, at your personal tax rate. Prerequisite: The payout occurs after your 62nd birthday, and the contract has been in effect for at least twelve years (62/12 rule).
In the event of death
In a standard securities account
The securities account value falls into the estate. Inheritance tax is incurred on the value, and capital gains tax on the profit once the heirs sell.
In an insurance wrapper
The death benefit of a life insurance policy is exempt from income tax. Whether inheritance tax is incurred depends on the structure. More on this in the section on succession.
The same investment, once in a regular custody account and once within an insurance wrapper. The difference primarily arises because earnings within the insurance wrapper are not taxed during the term and remain fully invested.
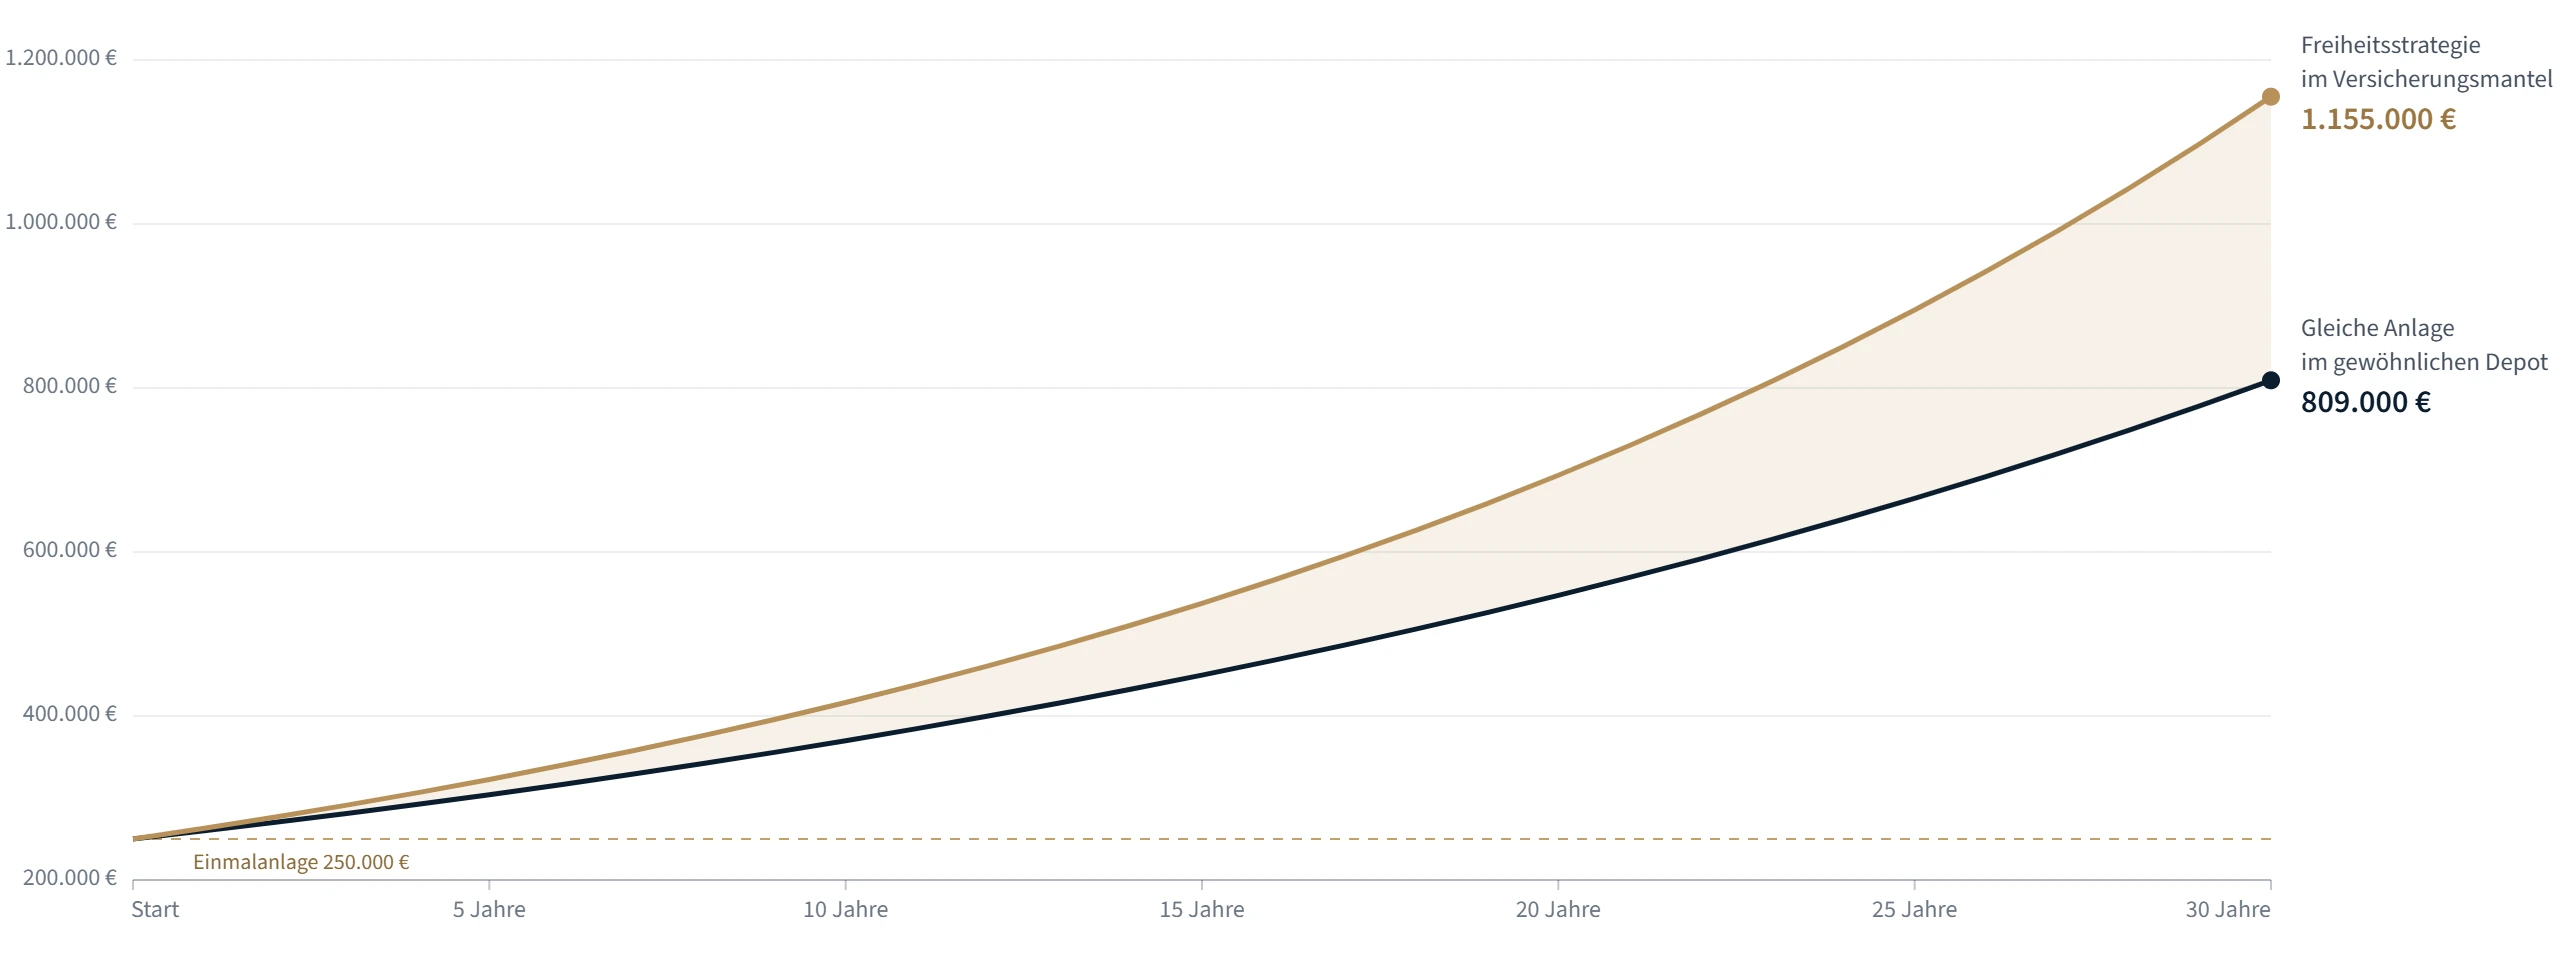
Model calculation: 55-year-old investor, one-time investment of €250,000, 7% annual return. The performance accounts for the following costs: Freedom Strategy: 1.49% per year and a 5% performance-based fee. Standard securities account: 1.29% per year and a 5% performance-based fee, with an annual deduction of 26.375% settlement tax including the solidarity surcharge on returns. Future performance is not guaranteed.
We are not tax advisors. Estably is a wealth management firm and offers neither tax nor legal advice. This description explains the general functionality and does not replace an assessment of your individual case. How the legal framework affects you depends, among other things, on your domicile, tax rate, age, marital status, and term. We recommend that you discuss this with your tax advisor before concluding a contract.
A policy can be transferred during one's lifetime. If 99 percent is gifted and one percent retained, the current value is transferred. You retain a say in accessing the capital through the remaining share. Future value appreciation already benefits the recipient.
Calculated Example
€400,000 is invested and grows over 31 years at 7% per year to approximately 3.25 million. The daughter is the sole heir. A standard securities account is compared with a policy that was 99% gifted at the start.
In a standard securities account
That is 45% of the €2.85 million profit.
With the Freedom Strategy
The gift of €396,000 remains below the gift tax allowance for children of €400,000, and death benefits from life insurance policies are exempt from income tax.
What to note about this example. It contrasts an unfavorable and a favorable case. The €541,500 results from deducting the child's allowance of €400,000 from the total value and taxing the remainder at 19%. The fact that the allowance coincidentally matches the investment sum can make the calculation misleading. The €751,688 is only incurred if the heiress actually sells the assets. The value of zero assumes that the daughter's allowance was not used otherwise, the arrangement is recognized by the tax authorities, and the current legal situation remains for 31 years.
For investors who plan for the long term and wish to pass their assets on to the next generation in an orderly manner.
Selected individual stocks, physically backed gold and silver ETFs, a Bitcoin ETP, and a position in Swiss Francs. The Friedrich Strategie GmbH team contributes its analyses and assessments to the investment process. Estably makes and is responsible for the investment decisions.
The assets are held via Liechtenstein Life Assurance AG at St. Galler Kantonalbank, predominantly via SIX SIS. The Cantonal Bank is 51% owned by the Canton of St. Gallen, which is liable for its obligations insofar as the bank's assets are insufficient.
According to Liechtenstein insurance supervision law, the investments form separate assets. If the insurer becomes insolvent, they do not fall into the insolvency estate but are treated with priority.
Additional payments are possible at any time and without limit; withdrawals are also possible, as long as at least 100,000 remains in the contract. A payout usually takes a few business days, in exceptional cases up to one month.
The composition is the same for all clients.
The contract can be terminated at any time. However, the tax advantages are tied to a minimum term and the age at payout. In the event of early termination, they are wholly or partially lost. The strategy is therefore designed for a long investment period.
In addition to the management fee, 0.50% per year is charged for the custodian bank and the insurance wrapper.
Ongoing, per year
Performance-based
5 %
on the profit, but only when your portfolio reaches a new high. According to the high-water mark principle, it only applies again when this high is exceeded, and not merely when the portfolio recovers after a decline.
What is not charged
There are no closing or distribution costs for the policy, no front-end loads, and no cancellation fee. The ongoing costs are deducted from the invested assets; you do not have to transfer anything separately.
The tax advantage assumes that current rules remain in place and that you comply with the conditions until the end of the term.
The advantage depends on tax law. The half-taxation, allowances, and treatment of the death benefit comply with current law. Over a period of thirty years, this may change. The current calculation is based on current rules.
The Freedom Strategy applies only to German taxpayers. The described effects refer to private individuals who are unlimitedly tax-liable in Germany.
The advantage is forfeited upon early withdrawal. Half-taxation does not apply before the 62nd birthday and before the expiration of a twelve-year term.
The investment corresponds to the Shielding Strategy. Approximately three-quarters of the portfolio is invested in companies, supplemented by gold and silver, and a small Bitcoin position.
An Additional Contractual Partner. In addition to the custodian bank, Liechtenstein Life Assurance AG is your contractual partner. The investment constitutes segregated assets and is legally protected.
Freedom Strategy
Shielding Strategy
Investments are made in
Freedom Strategy
Individual stocks, gold and silver ETFs (physically backed), Bitcoin ETP, and Swiss francs
Shielding Strategy
The same assets, gold physically stored
Legal framework
Freedom Strategy
Unit-linked life insurance with Liechtenstein Life
Shielding Strategy
Securities account in your name
Custody Bank
Freedom Strategy
St. Galler Kantonalbank
Shielding Strategy
Liechtensteinische Landesbank
Ongoing Costs
Freedom Strategy
0.99% management fees plus 0.50% for the custodian bank and insurance wrapper
Shielding Strategy
0.99% management fees plus 0.30% custody fees
Tax on rebalancing
Freedom Strategy
Not applicable during the term
Shielding Strategy
Capital gains tax on every realized profit
Suits you if
Freedom Strategy
You want to invest for the long term, take advantage of tax benefits, and have your assets held in Switzerland.
Shielding Strategy
You want to have your assets managed flexibly in your own custody account in Liechtenstein.
The Freedom Strategy and the Shielding Strategy pursue the same investment approach, but they differ in their legal and tax structure. Together, we will determine which option is more suitable for your situation.
Am I tied down by the insurance wrapper?
No, liquidation is possible at any time.
What is the 62/12 rule?
For life insurance contracts concluded since 2005, only half of the difference between the payout and the contributions paid is taxed. The prerequisite is that the payout occurs after the completed 62nd year of age and the contract has been in effect for at least twelve years. Otherwise, the full return is taxed.
Which insurer is the partner?
Liechtenstein Life Assurance AG, based in Liechtenstein, founded in 2008, supervised by the Liechtenstein FMA and part of the prosperity company AG.
How do I switch from the Shielding Strategy?
In a personal consultation, we assess whether the switch makes sense for you and take care of the process.
How quickly can I access my money?
Usually a few business days after the payout request, in exceptional cases up to one month.
Can I influence the composition?
No, it is the same for all clients. We consider individual specifications from Estably Premium, i.e., from €1 million.
We would be happy to discuss this with you personally. Together, we can calculate whether the insurance wrapper is worthwhile in your situation.